
Is Travel Insurance Worth It? Real Client Stories + Expert Advice From a Travel Advisor
The quick answer: Yes, travel insurance is worth it for most travelers. A comprehensive policy typically costs 4% to 10% of your prepaid, nonrefundable vacation cost. On a $5,000 honeymoon or cruise, that’s roughly $200 to $500 to protect the whole investment from illness, weather delays, missed connections, medical emergencies abroad, and lost luggage. Without it, one bad week can cost you everything you paid.
Planning a vacation is one of my favorite parts of what I do.
Whether it’s a romantic honeymoon, a long-awaited family vacation, a cruise, or a destination wedding surrounded by everyone you love, so much excitement goes into choosing the destination, the resort, the flights, and all the little details that make it special.
But after nearly a decade in this industry, I’ve learned something very important:
You can plan everything perfectly… and still have things go wrong.
Winter storms. Flight delays. Medical emergencies. Missed connections. Illness right before departure.
These are not rare situations. They happen every single season.
And this is exactly where travel insurance stops being an “extra” and becomes a true safety net.
Travel insurance protects your investment when life happens. It’s what stands between you and losing thousands of dollars if you can’t travel, if your vacation is delayed, or if you need help while you’re far from home.
I’ve seen firsthand how much of a difference it makes. So let’s talk about why you shouldn’t skip it, what it actually covers, and how to choose the right policy for your adventure.
Real Stories: What Happens With (and Without) Travel Insurance
Every policy I recommend comes back to moments like these.
Story 1: Two snowstorms, one vacation, zero dollars lost
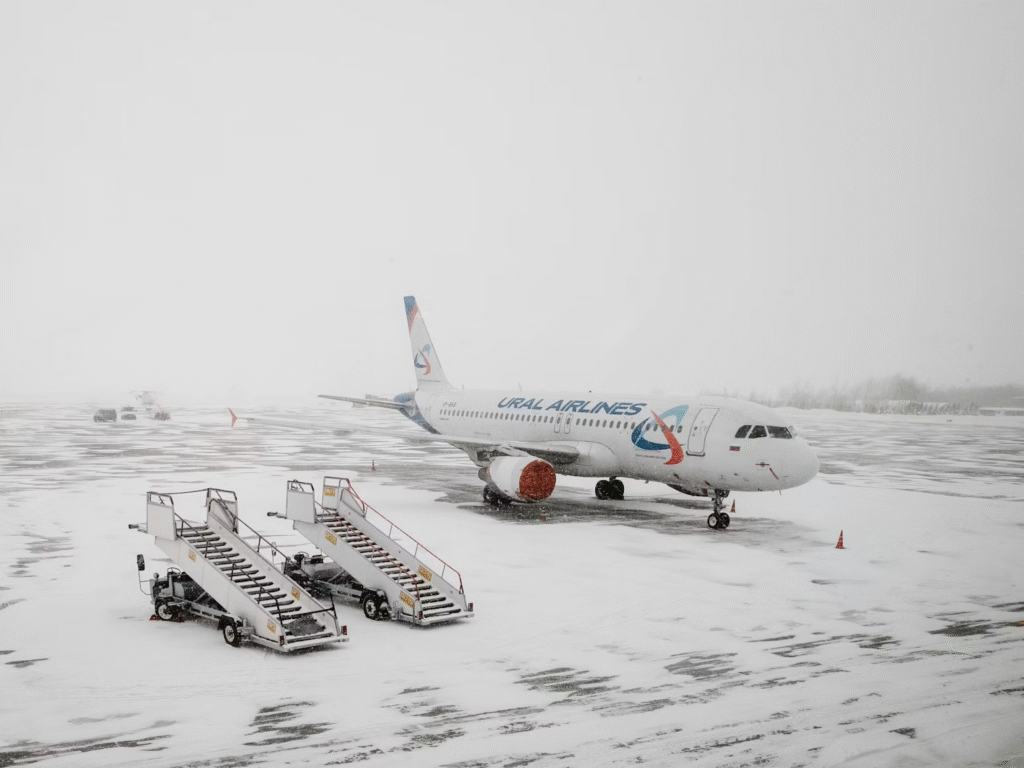
In late January 2026, a massive winter storm swept across much of the country and canceled thousands of flights. My client’s vacation was scheduled for that exact week.
Her flight was delayed. Then delayed again. And again.
We made the call to cancel and rebook her for the following week… and then a second winter storm rolled through the Southeast and hit her new travel dates, too.
Two storms. Two sets of travel dates. One very tired traveler.
Because she had travel insurance on her booking, she did not lose a single dollar of her vacation investment. She was also reimbursed for the expenses she paid for at the airport while she waited out the delays.
Picture how differently that week would have gone without coverage.
Story 2: The illness that cost a couple almost everything
I once worked with clients who decided to skip insurance to save a little money. A few days before their vacation, one of them became ill, and their doctor advised them not to travel.
Because they didn’t have coverage, they lost almost the entire cost of their vacation. No refund. No credit. Just a very expensive and heartbreaking lesson.
Story 3: The missed cruise connection
On the other hand, I had a couple traveling in the winter who did buy insurance. A snowstorm caused them to miss their connection on the way to their cruise.
They needed an overnight hotel stay, new flights, and meals while they waited. Their insurance covered those unexpected expenses. Instead of worrying about the cost, they were able to focus on getting to the ship and still enjoying their vacation.
Those experiences are why I am such a strong believer in travel insurance.
It’s not about expecting something to go wrong. It’s about being prepared if it does.
“But Isn’t Travel Insurance Too Expensive?”
No. Travel insurance usually costs a small slice of what it protects.
This is the number one objection I hear, and I get it. When you’re already investing thousands in a vacation, honeymoon, or destination wedding, adding a few hundred dollars more can feel like a lot.
Here’s the reality check:
That $250 policy can protect a $5,000+ vacation.
Without it, one unexpected event (illness, a weather delay, a family emergency, lost luggage) could cost you everything you paid.
Let me break down the math:
- Typical cost of a vacation for a couple: $4,000 to $8,000
- Typical cost of travel insurance: 4% to 10% of your prepaid, nonrefundable costs, or about $200 to $500 on a $5,000 vacation
- Cost of losing your entire vacation: 100% of what you paid
When you look at it that way, insurance isn’t expensive.
Losing your entire vacation because you didn’t have it? That’s expensive.
“Doesn’t My Credit Card Cover Travel Insurance?”
Sometimes, but usually not enough. Some premium credit cards include travel protections, but the coverage is typically limited and full of restrictions.
Here’s what most people don’t realize about credit card coverage:
- Many cards cover trip delays but not trip cancellations
- You may have to book the entire vacation on that card
- Pre-existing medical conditions typically aren’t covered
- Coverage limits are much lower than a dedicated travel insurance policy
What your credit card might cover:
- Lost luggage (often with low limits, like $500 to $1,000)
- Travel delays (partial reimbursement)
- Rental car damage (primary or secondary coverage)
What your credit card usually won’t cover:
- Emergency medical care abroad
- Emergency medical evacuation
- Trip interruption for a family emergency back home
- Comprehensive baggage loss or delay
- “Cancel For Any Reason” protection
If your vacation costs $6,000 and your card only covers $1,000 in baggage loss, that’s a problem. Read the fine print carefully, and ask yourself whether it’s truly enough coverage.ther it’s truly enough coverage.
“Doesn’t My Health Insurance Cover Me Everywhere?”
Usually not outside the United States. This is a dangerous assumption, especially for international vacations and cruises.
Here’s the truth:
Medicare does NOT cover medical expenses outside the United States. If you or your travel companions are on Medicare and you need medical care abroad, you’re paying out of pocket. Medical emergencies overseas can cost tens of thousands of dollars.
Employer health insurance often has limited or no international coverage. Some plans cover emergency care abroad, but many don’t. And even if they do, you might need to pay upfront and get reimbursed later, which can be financially devastating.
What happens if you need emergency medical evacuation? Air ambulance services can cost $50,000-$100,000+. Most health insurance plans don’t cover this at all.
Travel insurance fills these gaps with:
- Emergency medical coverage abroad
- Emergency medical evacuation and repatriation
- 24/7 assistance services to help you find care
- Coverage that works anywhere in the world
Don’t gamble with your health coverage when you’re thousands of miles from home.
What Does Travel Insurance Actually Cover?
A good comprehensive policy covers seven big things. Let me walk you through each one.
1. Trip Cancellation Coverage
What it covers: If you need to cancel your trip before you leave due to a covered reason (illness, injury, death of a family member, natural disaster, etc.), you get reimbursed for your non-refundable expenses.
Why it matters: Honeymoons, destination weddings, and all-inclusive vacations often require deposits months in advance. If something happens and you can’t go, you don’t want to lose thousands of dollars.
Real example: Remember that couple who got sick before departure and lost their entire trip cost? Trip cancellation coverage would have saved them.
2. Trip Interruption Coverage
What it covers: If you have to cut your trip short and come home early due to a covered reason, insurance reimburses you for the unused portion of your trip plus the cost of getting home.
Why it matters: Family emergencies happen. If you need to fly home suddenly, you’re looking at last-minute flights (expensive!) plus losing the vacation days you already paid for.
3. Travel Delay Coverage
What it covers: If your trip is delayed for a covered reason (weather, mechanical issues, etc.), insurance reimburses you for additional expenses like hotels, meals, and transportation.
Why it matters: Remember the couple whose winter storm delayed their cruise departure? This coverage paid for their hotel, meals, and rebooking. Without it, they would have been out hundreds of dollars, plus stressed about the cost.
Important note: If your flight is delayed or canceled due to weather, the airline is NOT obligated to help you. Weather is considered an “act of God,” and you’re on your own for hotels and meals.
4. Emergency Medical and Dental Coverage
What it covers: Medical emergencies while traveling, including doctor visits, hospital stays, prescriptions, and emergency dental care.
Why it matters: If you’re traveling internationally and need medical care, costs can be astronomical. And as I mentioned earlier, Medicare doesn’t cover you outside the U.S.
5. Emergency Medical Evacuation
What it covers: If you need to be transported to a medical facility or evacuated back home due to a serious medical emergency.
Why it matters: Air ambulance and medical evacuation can cost $50,000-$100,000+. This is coverage you hope you never need, but if you do, it’s literally life-saving.
6. Baggage Loss/Delay Protection
What it covers: Reimbursement if your luggage is lost, stolen, damaged, or delayed.
Why it matters: Imagine your wedding dress or suit is lost on the way to your destination wedding. Or your luggage is delayed and you’re stuck without clothes and toiletries for days. Insurance covers the cost of replacing essential items so you’re not stuck.
7. 24/7 Emergency Assistance
What it covers: Access to a team that can help with medical emergencies, lost passports, emergency cash transfers, translation services, and more.
Why it matters: When you’re in a foreign country dealing with an emergency, having someone who can help you navigate the situation in real-time is invaluable.
Is “Cancel For Any Reason” Travel Insurance Worth It?
It can be, for high-stakes vacations like destination weddings and once-in-a-lifetime honeymoons. “Cancel For Any Reason” (CFAR) is an optional upgrade that lets you cancel for literally any reason and get back a portion of your costs.
Standard travel insurance only covers cancellations for the specific reasons listed in your policy. CFAR typically reimburses 50% to 75% of your prepaid, nonrefundable costs, no matter why you cancel.
When it makes sense:
- You’re booking far in advance and circumstances might change
- You’re nervous about work obligations or other commitments
- You want maximum flexibility
The catch:
- It costs more (usually adds 40-50% to your premium)
- You typically need to purchase it within 14-21 days of making your initial trip deposit
- You usually only get back 50-75% of costs, not 100%
It’s not for everyone, but for high-stakes trips like destination weddings or once-in-a-lifetime honeymoons, it can be worth it.
When Should You Buy Travel Insurance?
The short answer: As soon as you make your first trip payment.
That’s my answer every single time.
Here’s why:
- Time-sensitive benefits: Pre-existing condition waivers and CFAR coverage often require you to buy within days or weeks of your first deposit.
- Coverage starts sooner: If something happens between booking and departure, you’re protected.
- Waiting can cost you: Events that happen before you buy a policy generally aren’t covered.
Don’t wait until a few weeks before you leave. Buy it when you book.
How to Choose the Right Travel Insurance
I partner with three trusted travel insurance companies. Each offers tailored plans and 24/7 support, and the right one depends on your vacation, your budget, and who’s traveling.
Here are my top recommendations based on years of experience:
Travel Insured
- High limits for medical expenses and trip interruption
- Ideal for longer trips or those with significant financial investments
- Robust coverage options
- This is the company I quote for my clients alongside their custom proposal
- Get your Travel Insured quote here
Allianz Global
- Comprehensive coverage for single trips and multi-trip plans
- Rental car coverage available
- Great for budget-conscious travelers who still want solid protection
- Get your Allianz quote here
Arch RoamRight
- Reliable, comprehensive plans built to protect your vacation investment
- A solid option for cruises, all-inclusive resorts, and family vacations
- Get your Arch RoamRight quote here
How to decide:
Work with your travel advisor (hi, that’s me!) to look at the risks specific to your vacation and choose a plan that fits your budget and needs. When you book with me, travel insurance is part of my Signature Concierge Care, and I send you a quote right alongside your custom proposal so nothing slips through the cracks.
So, Is Travel Insurance Worth It? My Honest Take
Here’s how I think about it:
Travel insurance isn’t about whether something will go wrong. It’s about whether you can afford for something to go wrong without it.
If losing $5,000 to $10,000 wouldn’t be a financial burden for you, and you’re comfortable taking that risk, then maybe you skip it.
But for most people? That’s a lot of money to gamble with.
I’ve seen too many clients devastated by losing their entire vacation investment because they didn’t have coverage. And I’ve seen just as many clients relieved and grateful when their insurance saved them thousands during an emergency.
The peace of mind alone is worth it. Knowing that if something happens, you’re covered? That’s priceless.
Travel Insurance FAQs
Is travel insurance worth it for a cruise?
Yes. Cruises bring extra risks: a missed flight can mean missing the ship, and medical care on board or in port is often not covered by U.S. health insurance. An emergency evacuation from a Caribbean cruise ship to Miami can cost $50,000 to $75,000. A comprehensive policy with travel delay, missed connection, and medical evacuation coverage protects against all of that.
Does travel insurance cover flight cancellations due to weather or snowstorms?
Usually, yes. Most comprehensive policies list severe weather as a covered reason for travel delays, missed connections, and trip cancellation, as long as you bought the policy before the storm was named or forecast. Airlines must refund a canceled flight if you choose not to travel, but they don’t have to pay for hotels or meals during weather delays. Travel insurance can cover those costs.
Does my credit card’s travel insurance cover trip cancellation?
Sometimes, but it’s usually limited. Many cards cover only travel delays or lost luggage with low limits, and most require you to pay for the entire vacation with that card. Credit cards rarely include emergency medical care abroad, medical evacuation, or Cancel For Any Reason protection. Check your card’s benefits guide before you rely on it.
Does Medicare cover me when I travel outside the United States?
Generally, no. Original Medicare doesn’t pay for health care outside the U.S. except in rare situations. Some Medigap plans cover 80% of emergency care abroad after a deductible, with a $50,000 lifetime limit. A travel insurance policy with emergency medical and evacuation coverage fills the gap.
When should I buy travel insurance?
Buy travel insurance as soon as you make your first vacation payment. Many policies only offer pre-existing condition waivers and Cancel For Any Reason coverage if you buy within about 10 to 21 days of your first deposit. Buying early also means you’re covered for anything that happens between booking and departure.
How much does travel insurance cost?
Travel insurance typically costs 4% to 10% of your prepaid, nonrefundable vacation cost, and averages around 6%. For a $5,000 vacation, expect to pay roughly $200 to $500. Your price depends on your age, your vacation cost, your destination, and add-ons like Cancel For Any Reason.
Don’t Leave Home Without It
Whether you’re planning a romantic honeymoon, a destination wedding, a family vacation, or a long-awaited cruise, travel insurance is one of the smartest investments you can make.
It’s not just about protecting your money. It’s about protecting your peace of mind, so you can sink into that beach chair knowing you’re covered no matter what happens.
Nothing makes me happier than watching a client walk off the plane relaxed instead of worried about what could go wrong!
Ready to protect your next vacation? Get your travel insurance quote here in just a few minutes.
Planning a new adventure? Schedule a complimentary consultation with me, and let’s build your custom proposal with the right protection in place from day one.
Safe travels!
By Natasha Etheridge, owner of Serenity Sand & Seas Travel | Travel advisor since 2017 | ASTA member | Last updated November 2026
Disclosure: This post contains affiliate links. If you buy a policy through one of my links, I may earn a commission at no extra cost to you. I’m a travel advisor, not a licensed insurance agent, so always read the full policy before you buy.
